Duration turns a modest yield move into a larger bond price change
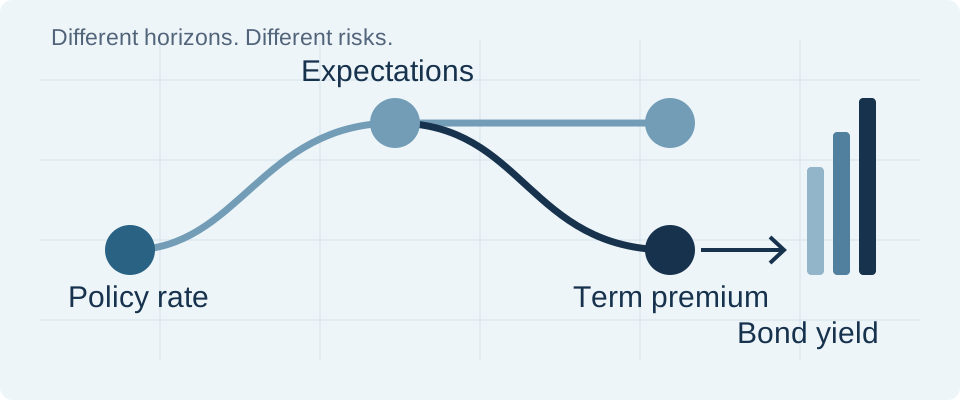
Use the DMO duration example to separate a bond's approximate price sensitivity from a policy forecast, convexity and the return after financing.
Research topic
Articles filed under this investing research topic.
Use the DMO duration example to separate a bond's approximate price sensitivity from a policy forecast, convexity and the return after financing.